

Buyers here have more leverage than they did a year ago on paper, and they are also taking 23 percent longer to actually write an offer. Those two things do not usually move together.
I pulled this month’s Orleans Parish condo data from the MLS looking at a 30-day closed window. I’m comparing it to our August 2025 report for the year-over-year read, and to the June and July 2026 reports for the recent trend.
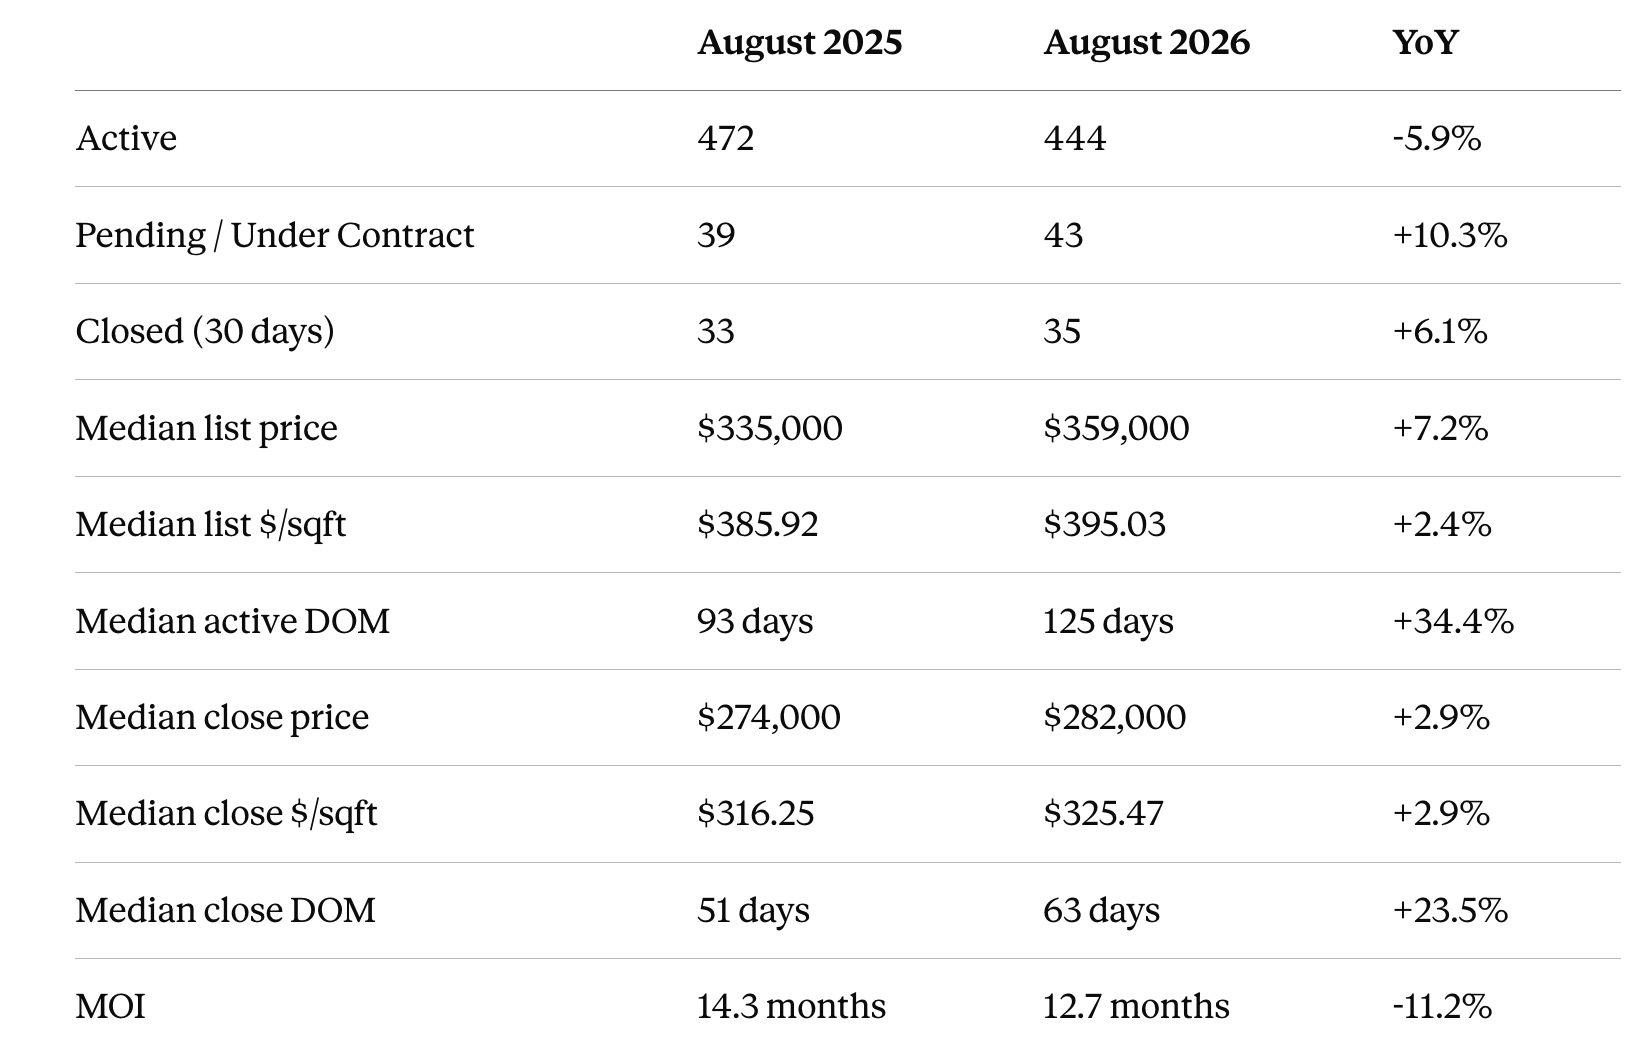
Price is up but not by much, and I would not call it real appreciation. Closed price and price per square foot are both up under 3% year over year. National inflation for the 12 months ending July 2026, the most recent data available, ran 3.4 percent. Condo prices here did not keep pace with that, so in real terms this is closer to flat than a gain, though it is nowhere close to a decline either. With only 33 closings last August and 35 this year, a point or two of that gap is tough to call out a trend.
The clearer sellers’ signal is inventory balance. MOI is tighter than a year ago, 12.7 versus 14.3, and pending contracts are up 10.3%, 43 versus 39. Under 6 months of inventory is a seller’s market. 12.7 is obviously nowhere close, but it points toward somewhat more leverage than sellers had in August 2025.
The number that cuts against that story is closed Days on Market (DOM). DOM tracks time from listing to accepted offer and it stops counting once a listing goes pending.
What DOM up 23.5% actually says is that buyers are taking longer to commit to an offer in the first place. Last year’s report had an explanation: higher insurance costs and rising HOA fees were keeping units on the market longer before an offer came in, especially above $400,000 or in buildings carrying assessment risk. A year later, buyers are taking longer to pull the trigger.
Here is how it breaks down from the past 90 days:
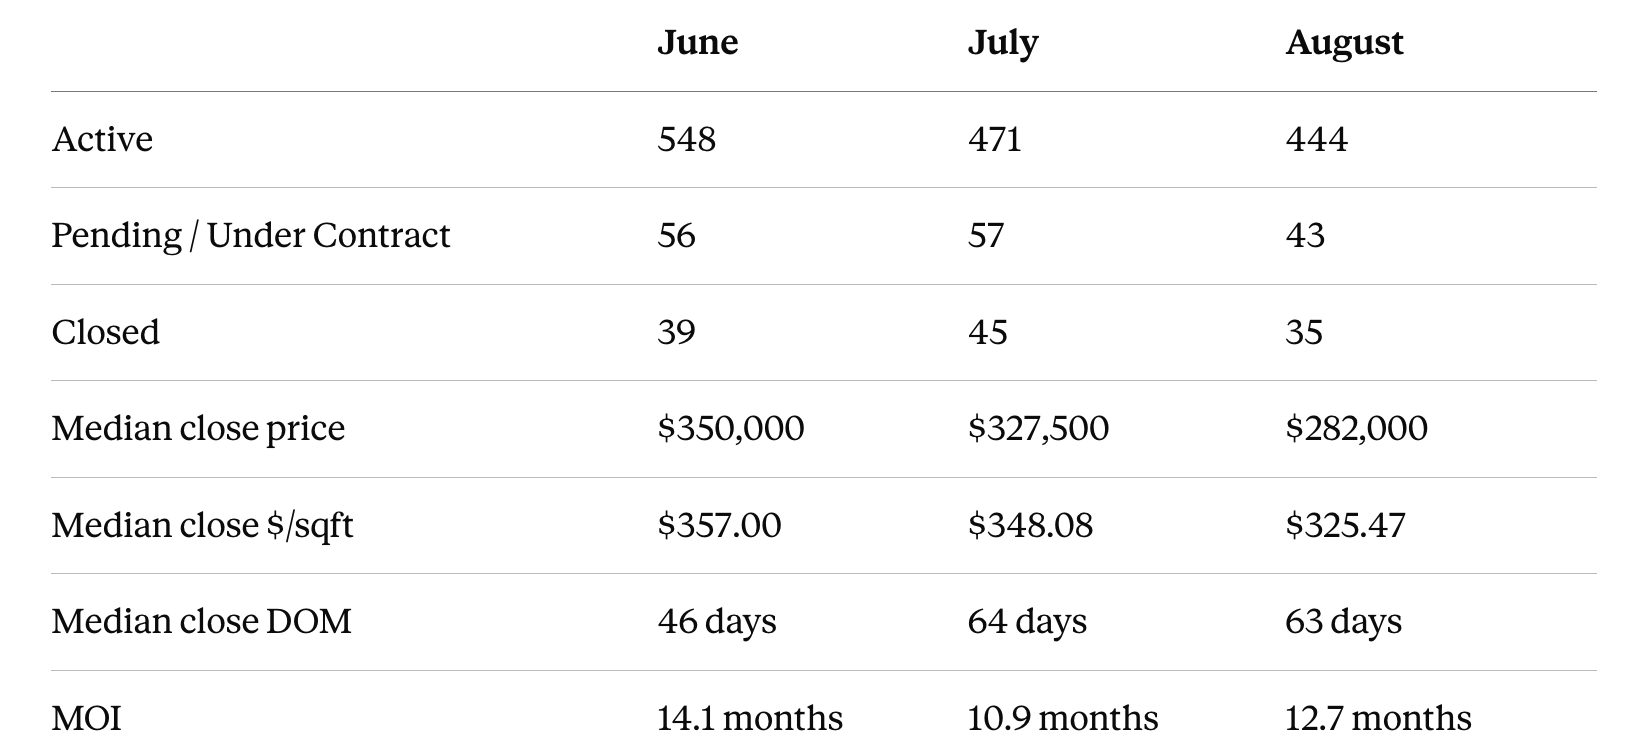
On its own, the price slide from June to August looks like a downturn. Last year’s August closed at a similar price and a similar MOI, so a real chunk of this slide is the normal seasonal pattern repeating. August is hot, kids are going back to school, and a lot people (an agents!) were sliding in last second travel.
Expect some seasonal pickup into fall, same as most years. What that seasonal bounce will not automatically fix is the DOM gap. That gap held up under a same-season comparison, so I am not assuming it resets just because the calendar does.
Lets’s go hyperlocal:
French Quarter
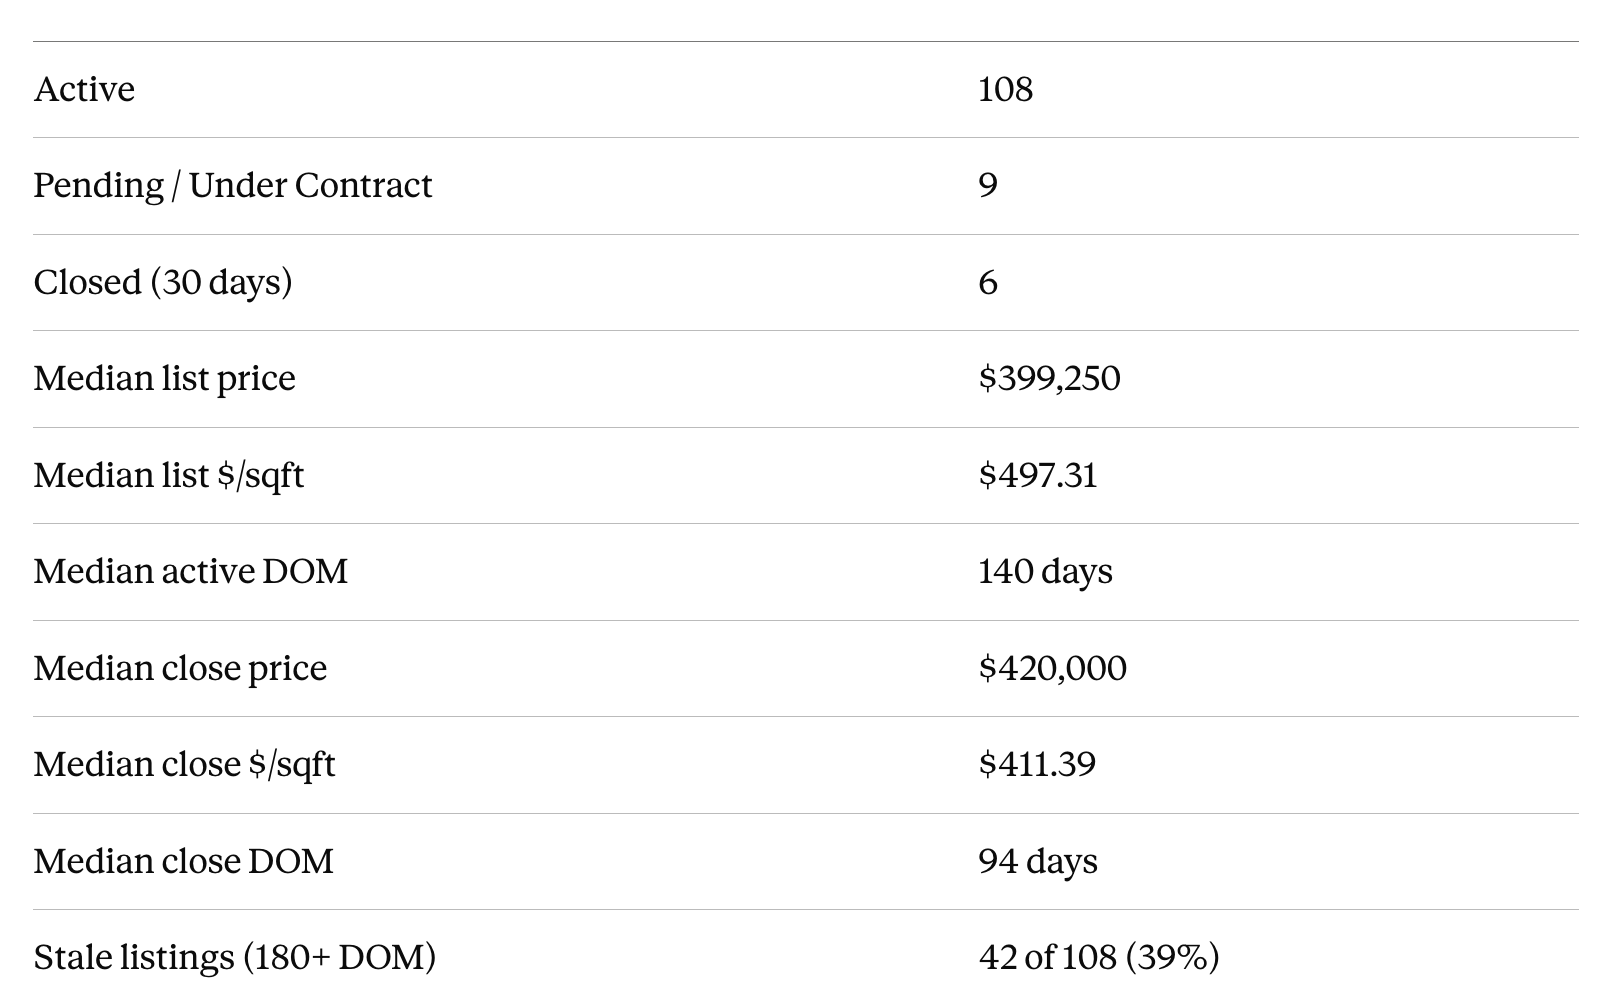
Worst stale rate of the six zones. Nine pending is tough compared to the 108 active.
FQ does have one thing going for it. A Fannie Mae rule change eliminated the requirement that blocked financing when more than half a building’s units were investor owned.
That rule kept some FQ buildings with heavy non-owner-occupied ownership out of reach for conventional loans It has technically been in effect since March, so it is not new, and it has not shown up in these numbers yet. Worth watching whether previously blocked buildings start moving as buyers and lenders catch up to it.
CBD/Warehouse
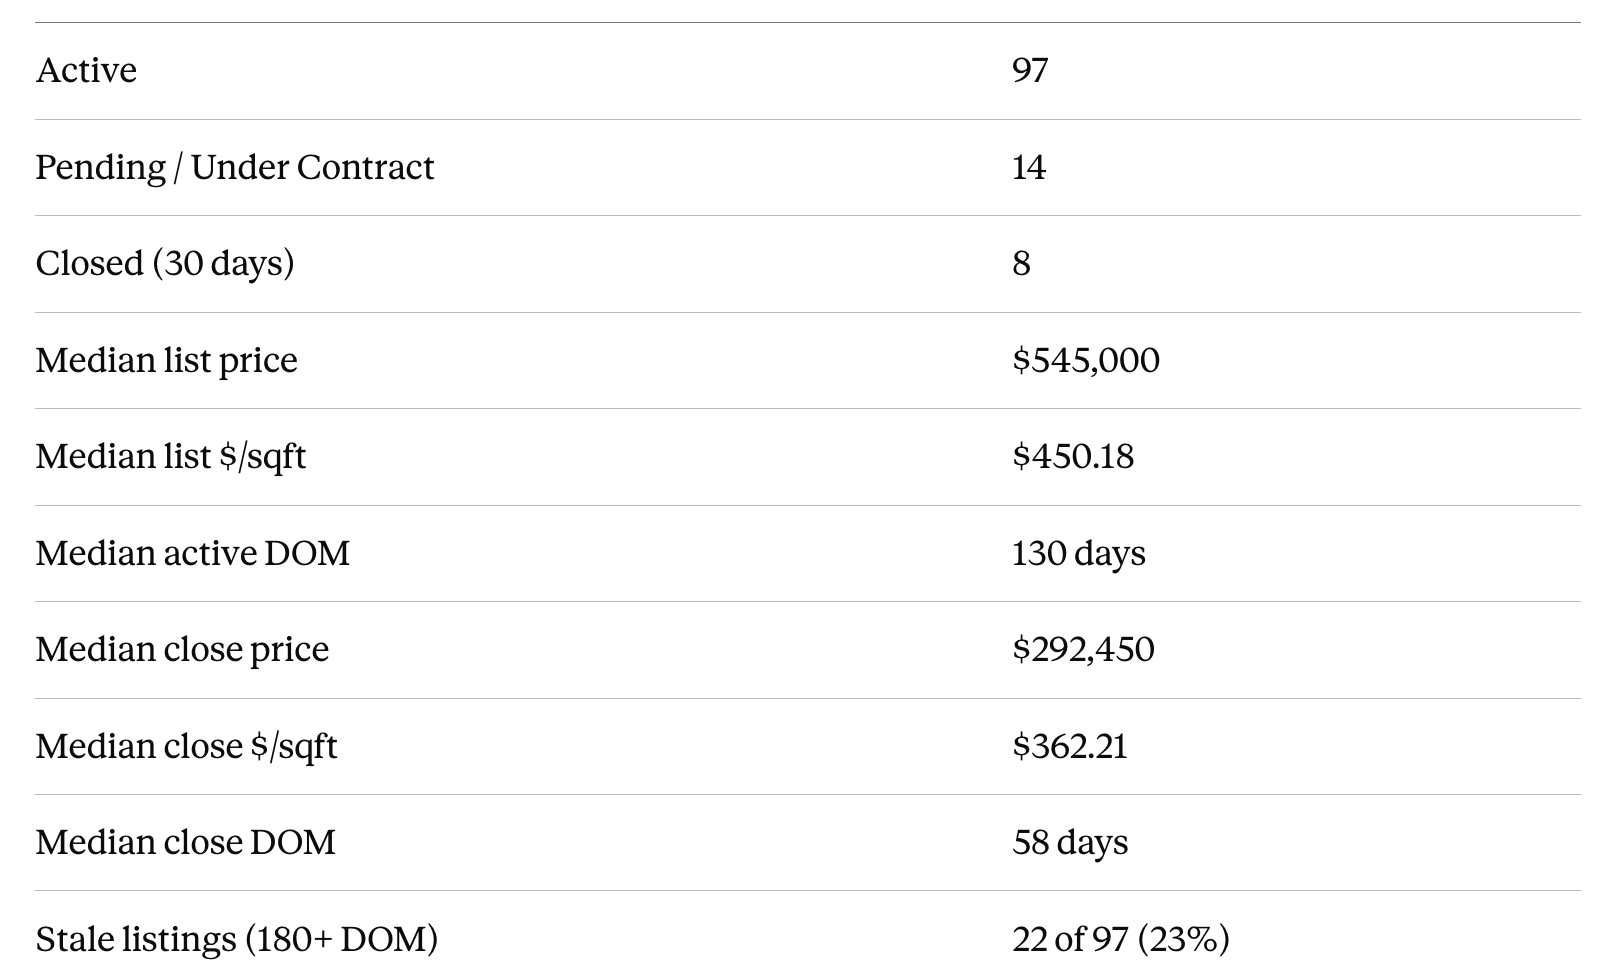
Highest pending count of the six zones. Most active buyer follow-through in the data right now.
Uptown/Garden District
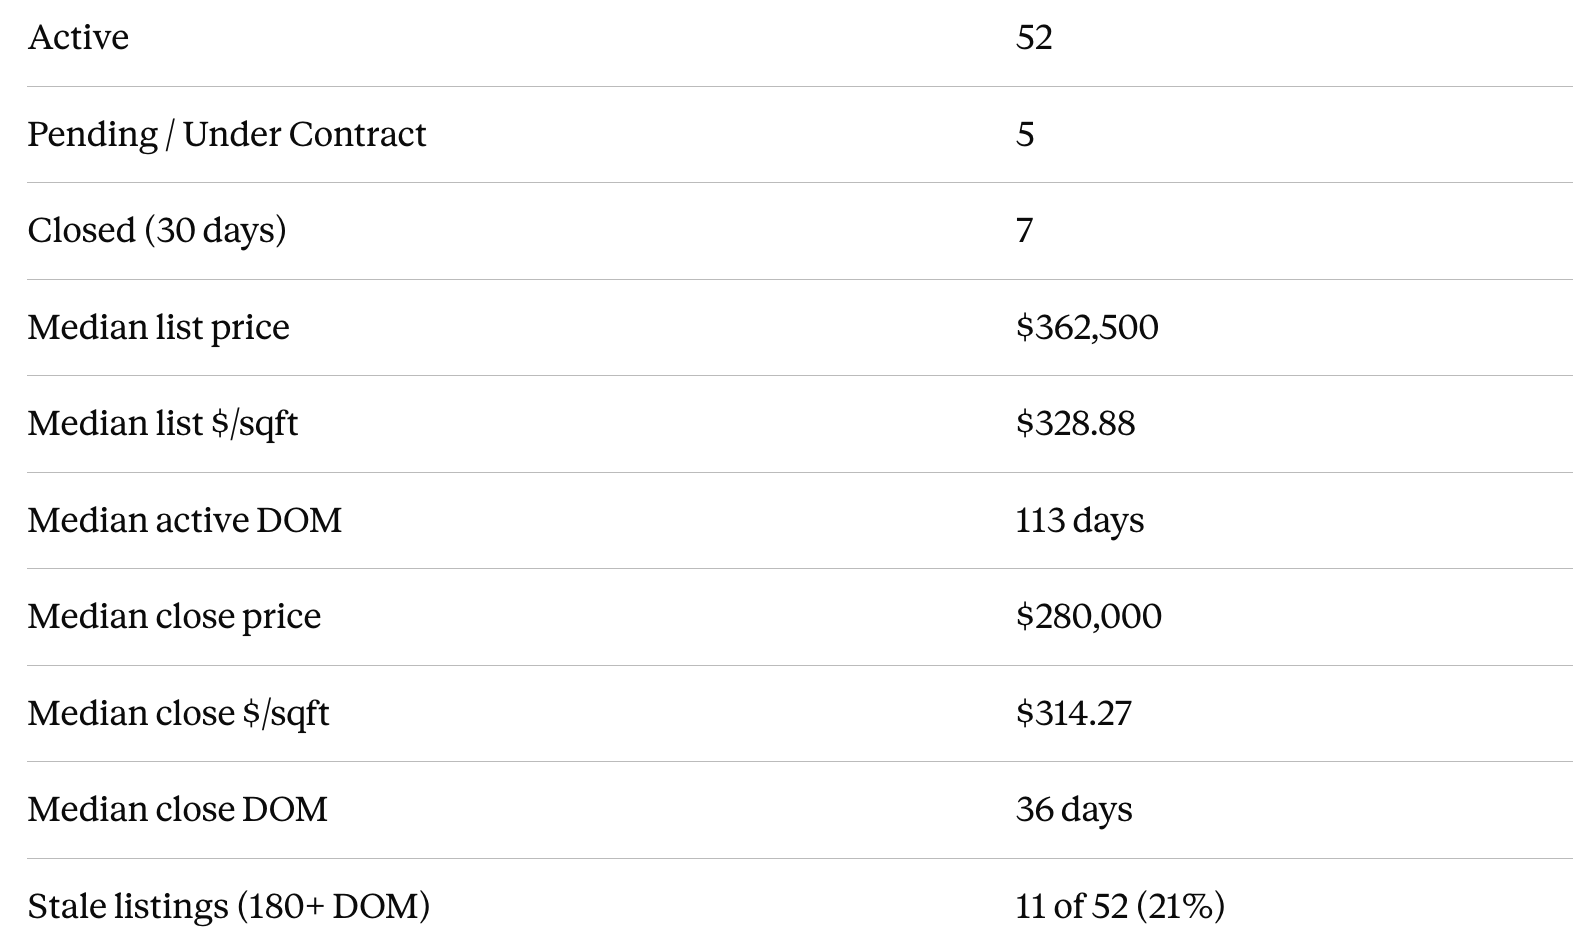
Fastest DOM of the six zones. Healthiest looking of the bunch.
St. Charles Corridor
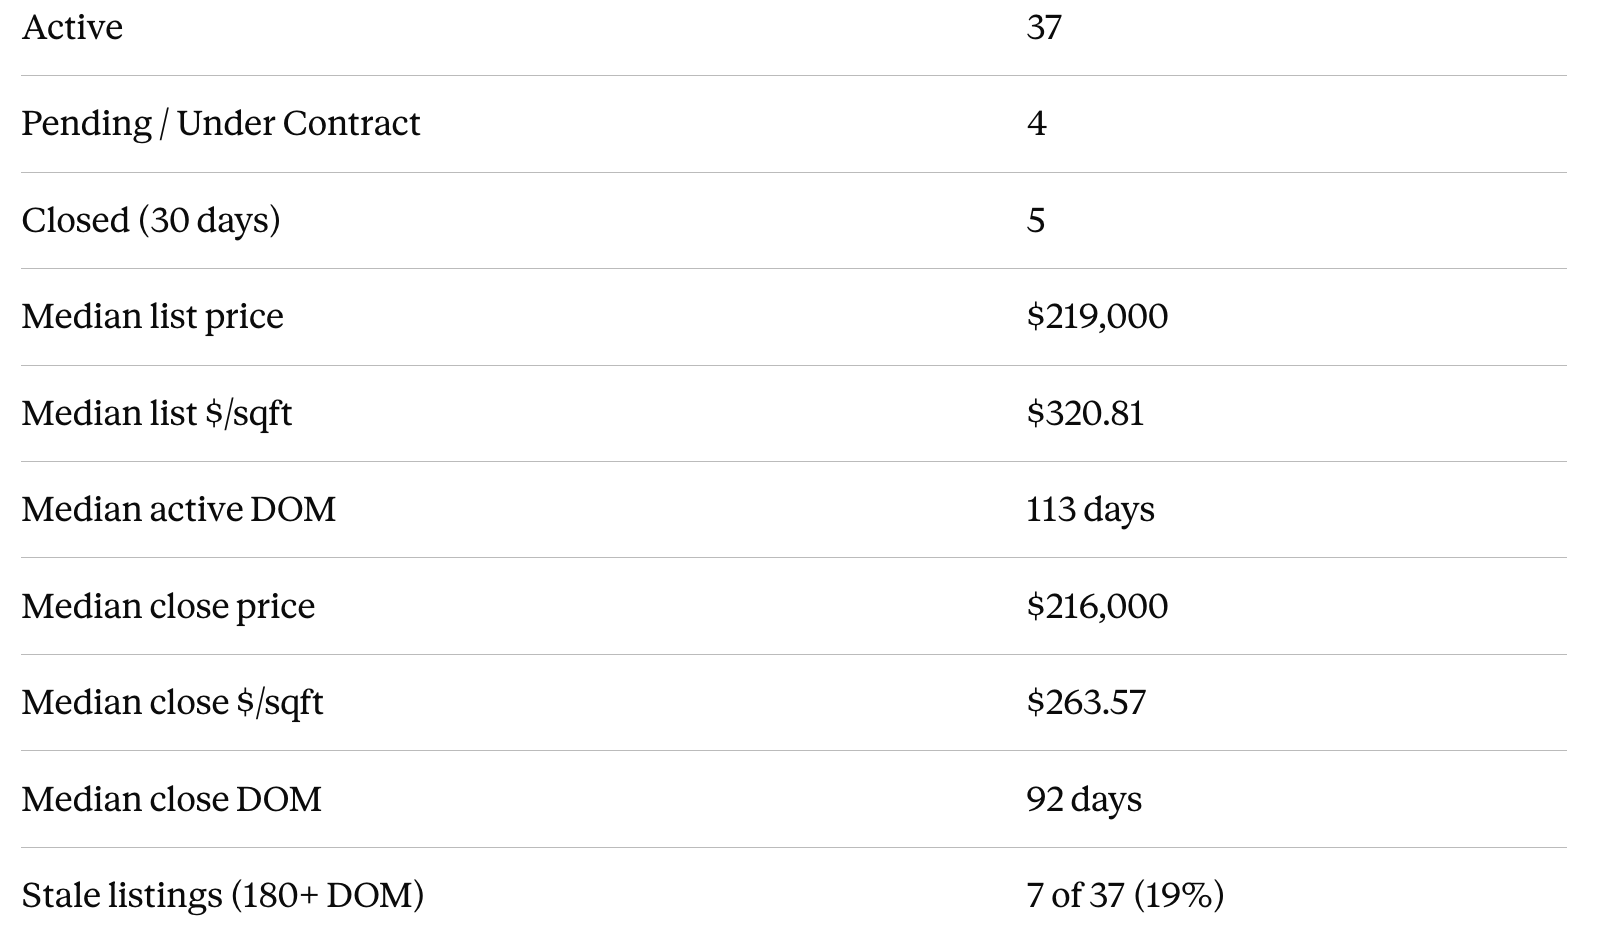
Lowest price point of the six zones by a wide margin. Makes sense too, right? This is your bulk of studio and 1bed apartments on the parade route.
Marigny/Bywater
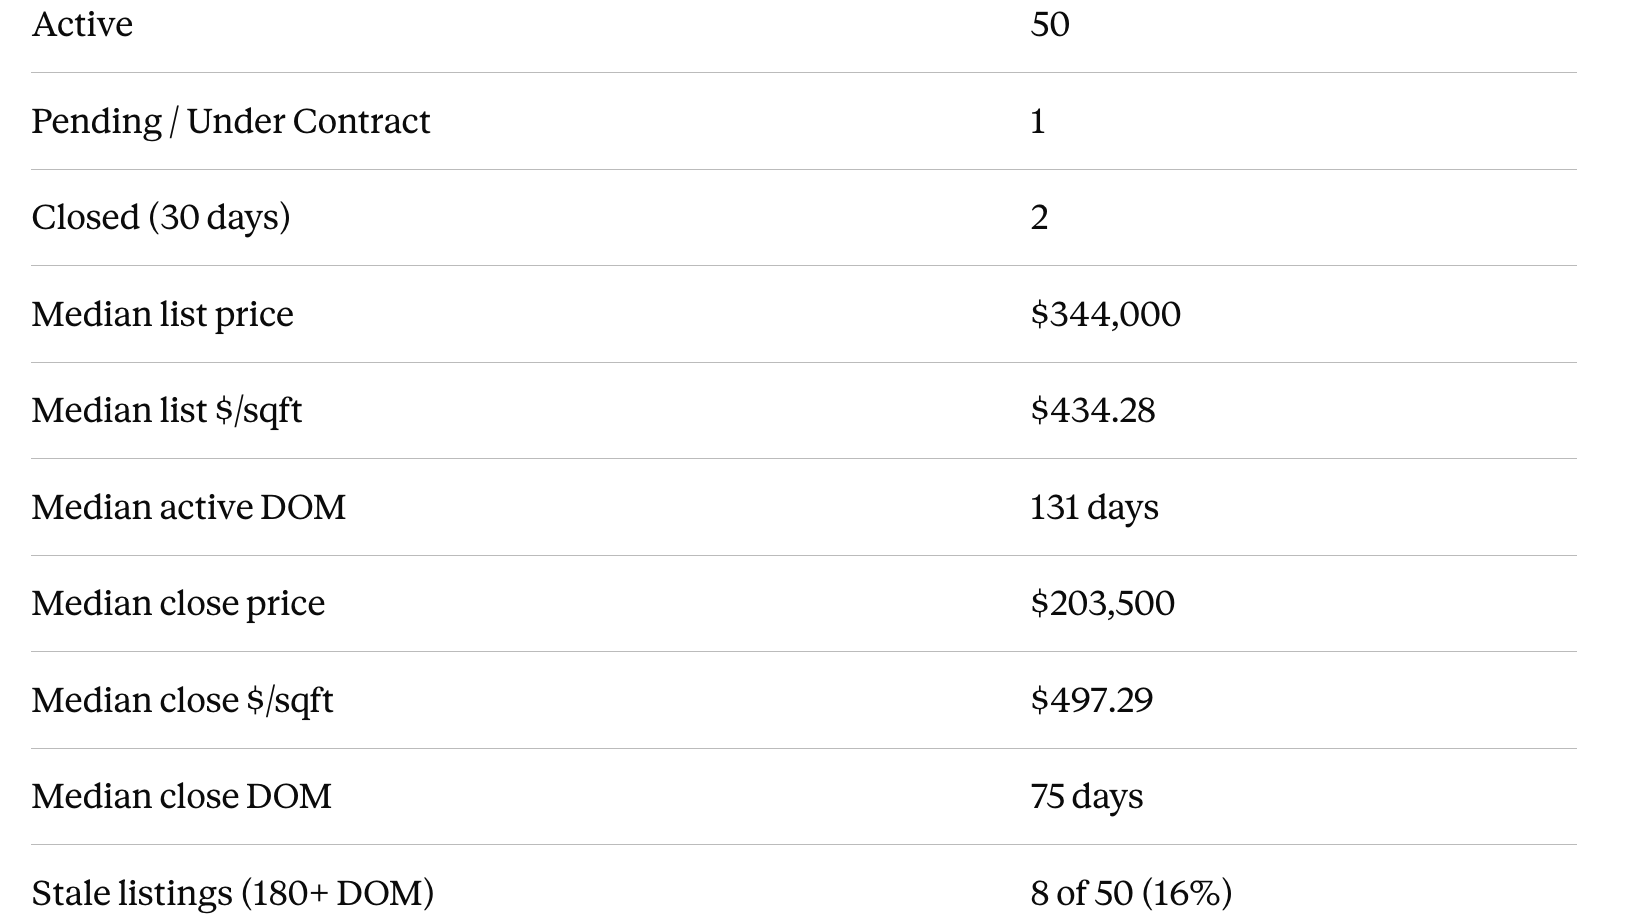
Only 2 closed and 1 pending against 50 active. Too thin to say anything about pace. Stale rate improved to 16 percent from 43 percent in the June report, the one clean improvement in the data even without enough closings to create a trend.
Lakefront
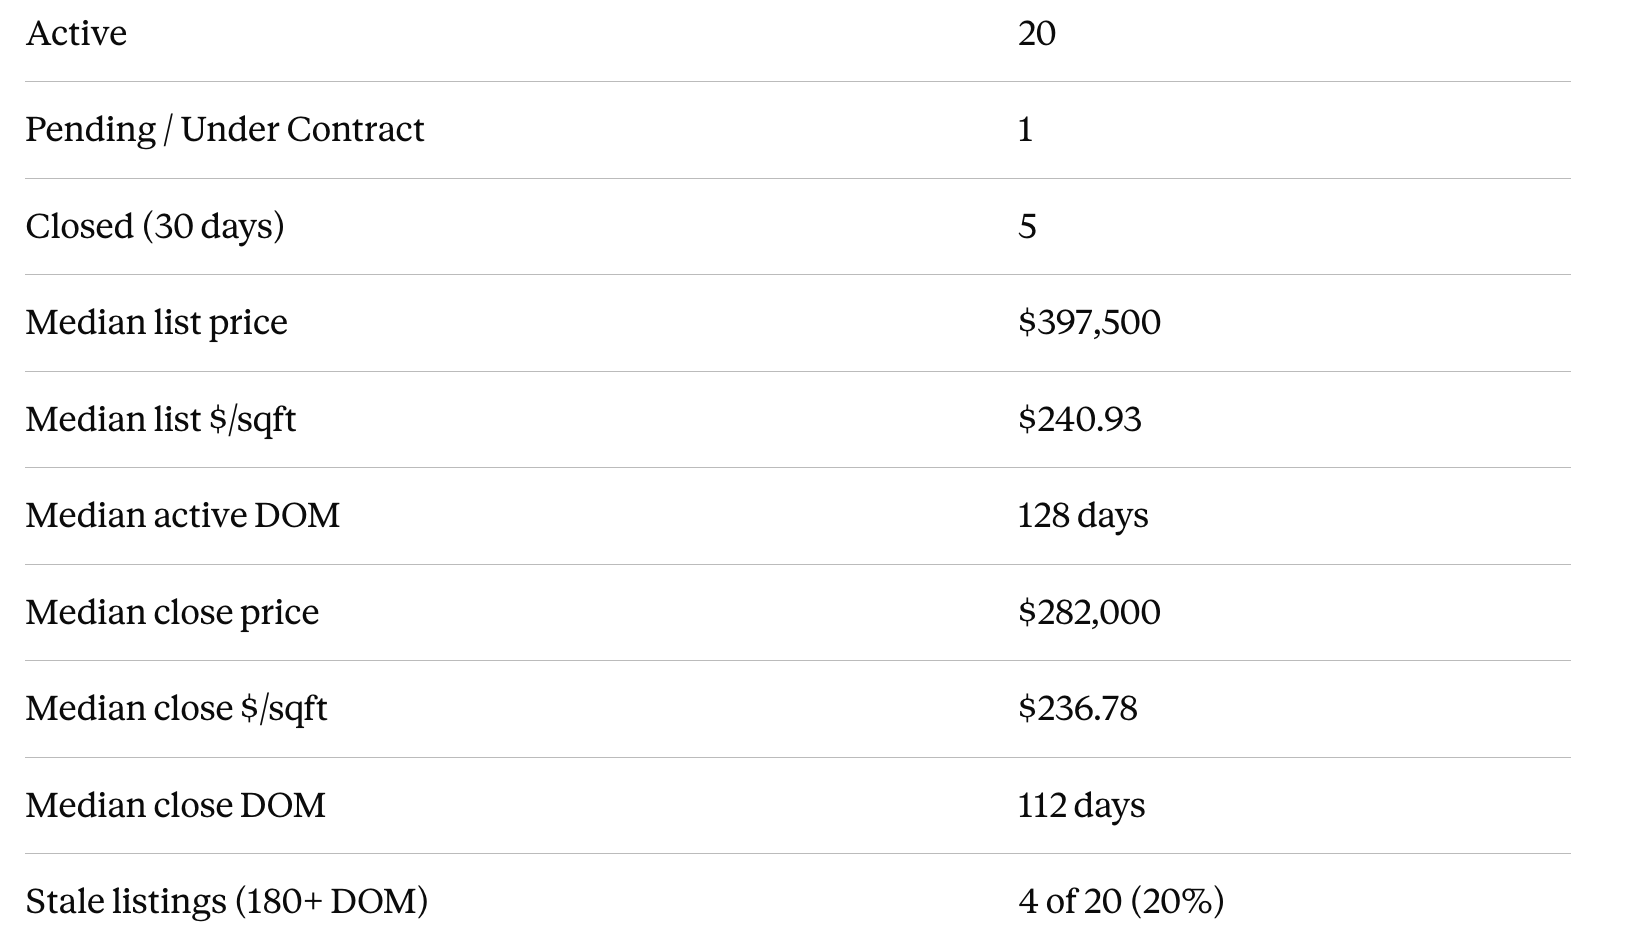
Same closed count as Marigny/Bywater against a fraction of the active pool. That ratio is the tightest of the six zones, even on a thin sample. If you are looking to sell your condo on the Lakefront, price it right and it should move.
So…
…this is not a one-directional story. Sellers have somewhat more leverage on paper than they did a year ago. Inventory is tighter, pending contracts are up, and price is holding roughly even with inflation.
What does not fit that story is how long it is taking to find a buyer in the first place, and insurance costs and HOA fee concerns, the same friction my own August 2025 report flagged, are the more likely reason why.
Uptown/Garden District and St. Charles Corridor are the two zones still moving at a normal pace. French Quarter has the most stale inventory in the city and CBD/Warehouse has the most buyers currently under contract.
Are you selling a condo right now, or holding off on making an offer?”
Philip Ewbank | New Orleans 8601 Leake Ave, New Orleans, LA 70118 | 504.335.7481