

Rates just crossed 7.5%, and seller financing is getting talked about as a popular workaround. There are 54 single-family homes in Orleans Parish offering it right now.
I pulled every active single-family listing in Orleans Parish from the MLS as of September 29, then pulled the ones advertising owner financing.
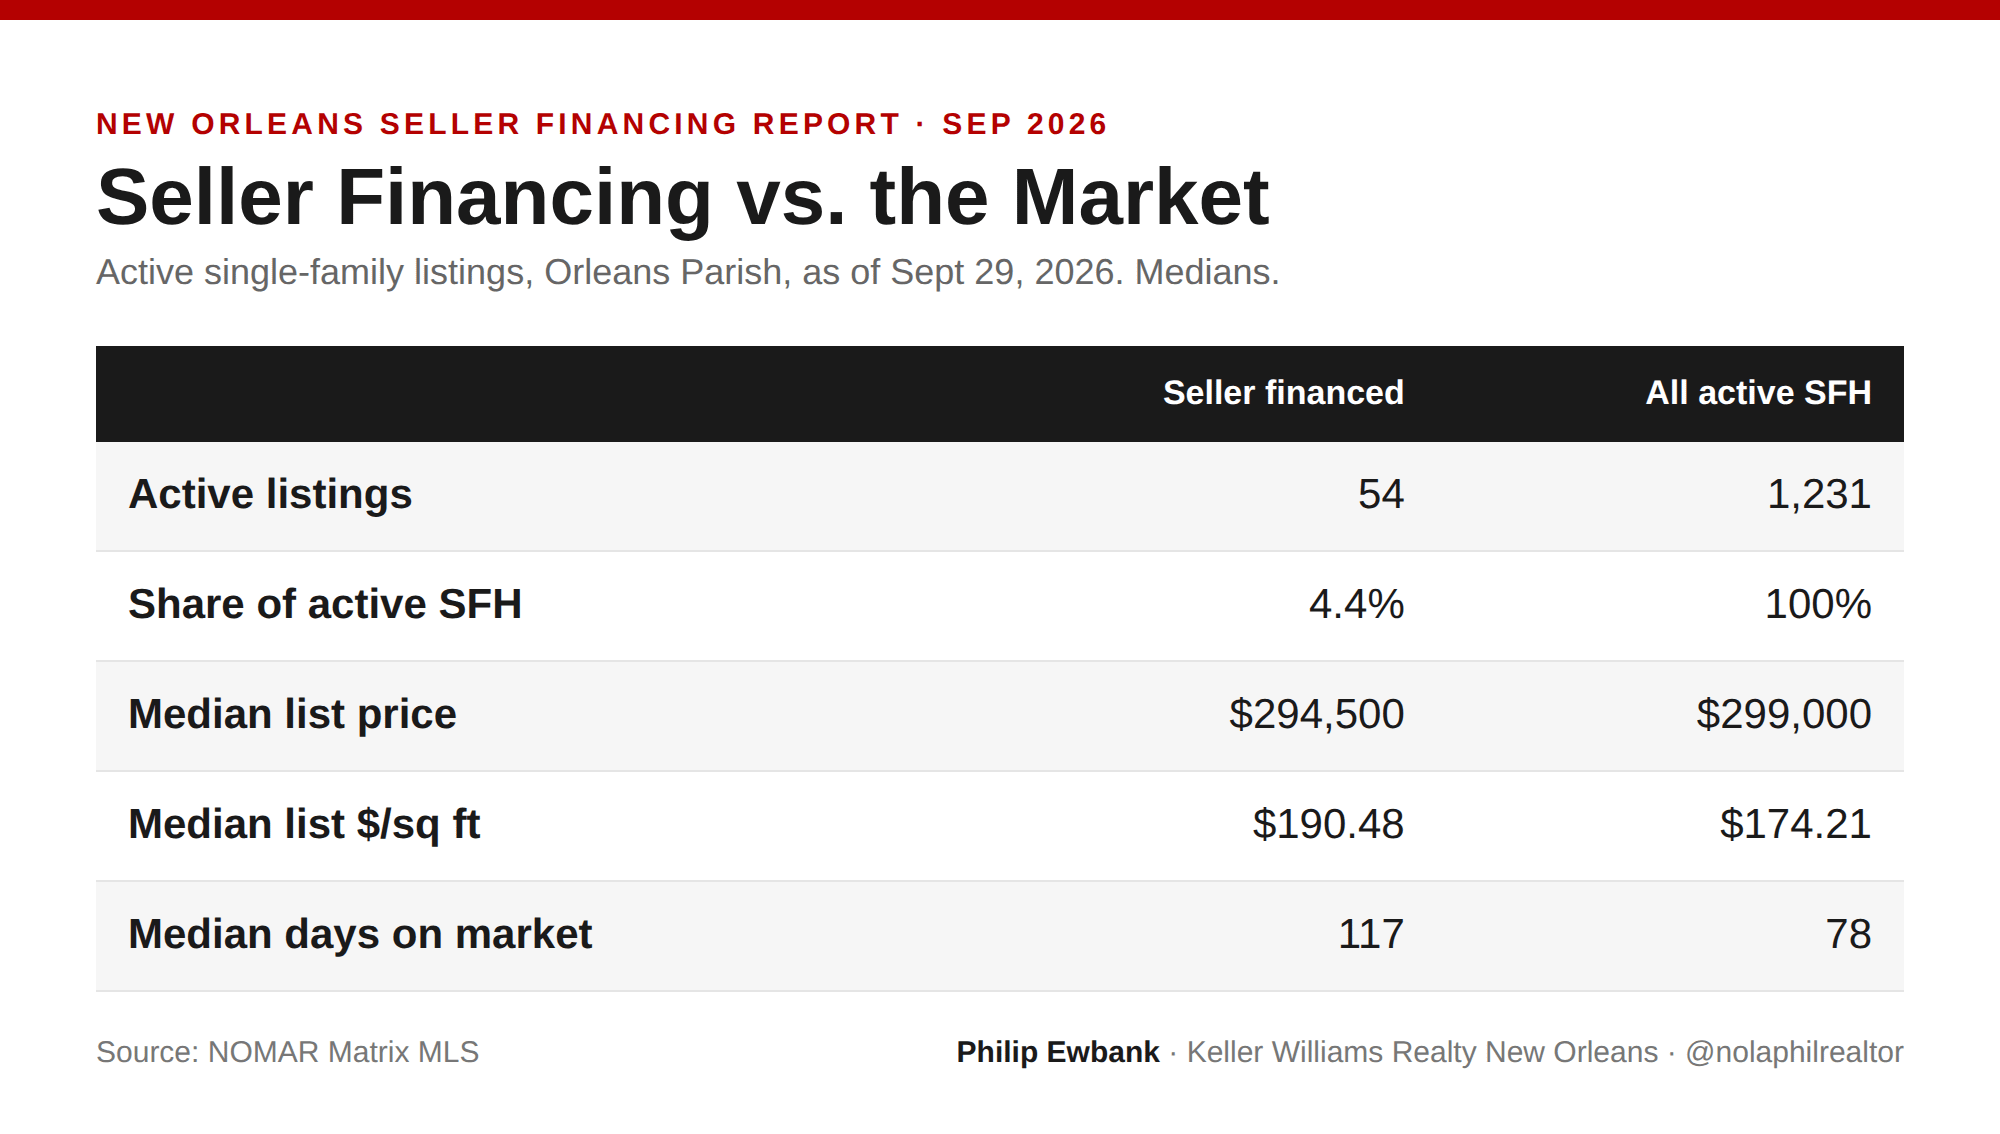
While both sets of homes are at the same price point, homes advertising Seller Financing are about 9% more expensive per square foot. Plus they have 39 more days on the market. My takeaway is that sellers would rather advertise they are offering Owner Financing than lower the price.
Seller financing works. It also shifts risk onto both sides of the table in ways most people do not think through until they are in it.
Sellers
If you are the seller, you are now the bank.
You need to underwrite your buyer. Bank statements, tax returns, a credit check. Most sellers and a lot of agents skip this.
Use a closing attorney who does owner financed deals regularly. The note language matters.
You can set the rules for all the terms: amortization schedule, interest rate, balloon payment, pre-payment penalty, missed payment penalties. This stuff is important.
Your buyer is now responsible for paying taxes and insurance on a property you still have money in. Set up a third party escrow to collect and pay both. If a payment gets missed and nobody catches it, your collateral is at risk.
If you still have a mortgage on the property, call your lender before you list this way. Your loan may not allow it.
Your equity is locked up until the balloon. A 3 year balloon usually means waiting 3 years for your money.
If the buyer stops paying, you are the one starting the legal process, taking the property back, and paying for repairs.
Talk to a CPA. Payments spread over time get taxed differently than a lump sum sale.
Buyers
If you are the buyer, the seller is doing you a favor, and the terms usually reflect that.
Expect a sizable down payment.
Expect the note to favor the seller. You can negotiate, but they hold the leverage.
The balloon is the real risk. You are betting you can refinance in 3 to 5 years. If rates, your credit, or the appraisal do not cooperate, you could lose the house and everything you put in.
Use an escrow company you choose to handle payments, taxes, and insurance. That gives you a record of every dollar.
Remember this is just the financing side of a transaction, you still need to do your inspections, appraisal, etc.
Have your own attorney review the note before you sign.
Ask whether the seller still has a mortgage on the property.
Ask whether your payments will be reported to the credit bureaus. If they are not, that works against your refinance plan.
Seller financing can be a good tool though it’s not a shortcut. The paperwork has to be right on both sides.
I put together a one-page checklist for each side, organized by deal stage, with the questions to ask before you sign anything. Save the one for your side below.
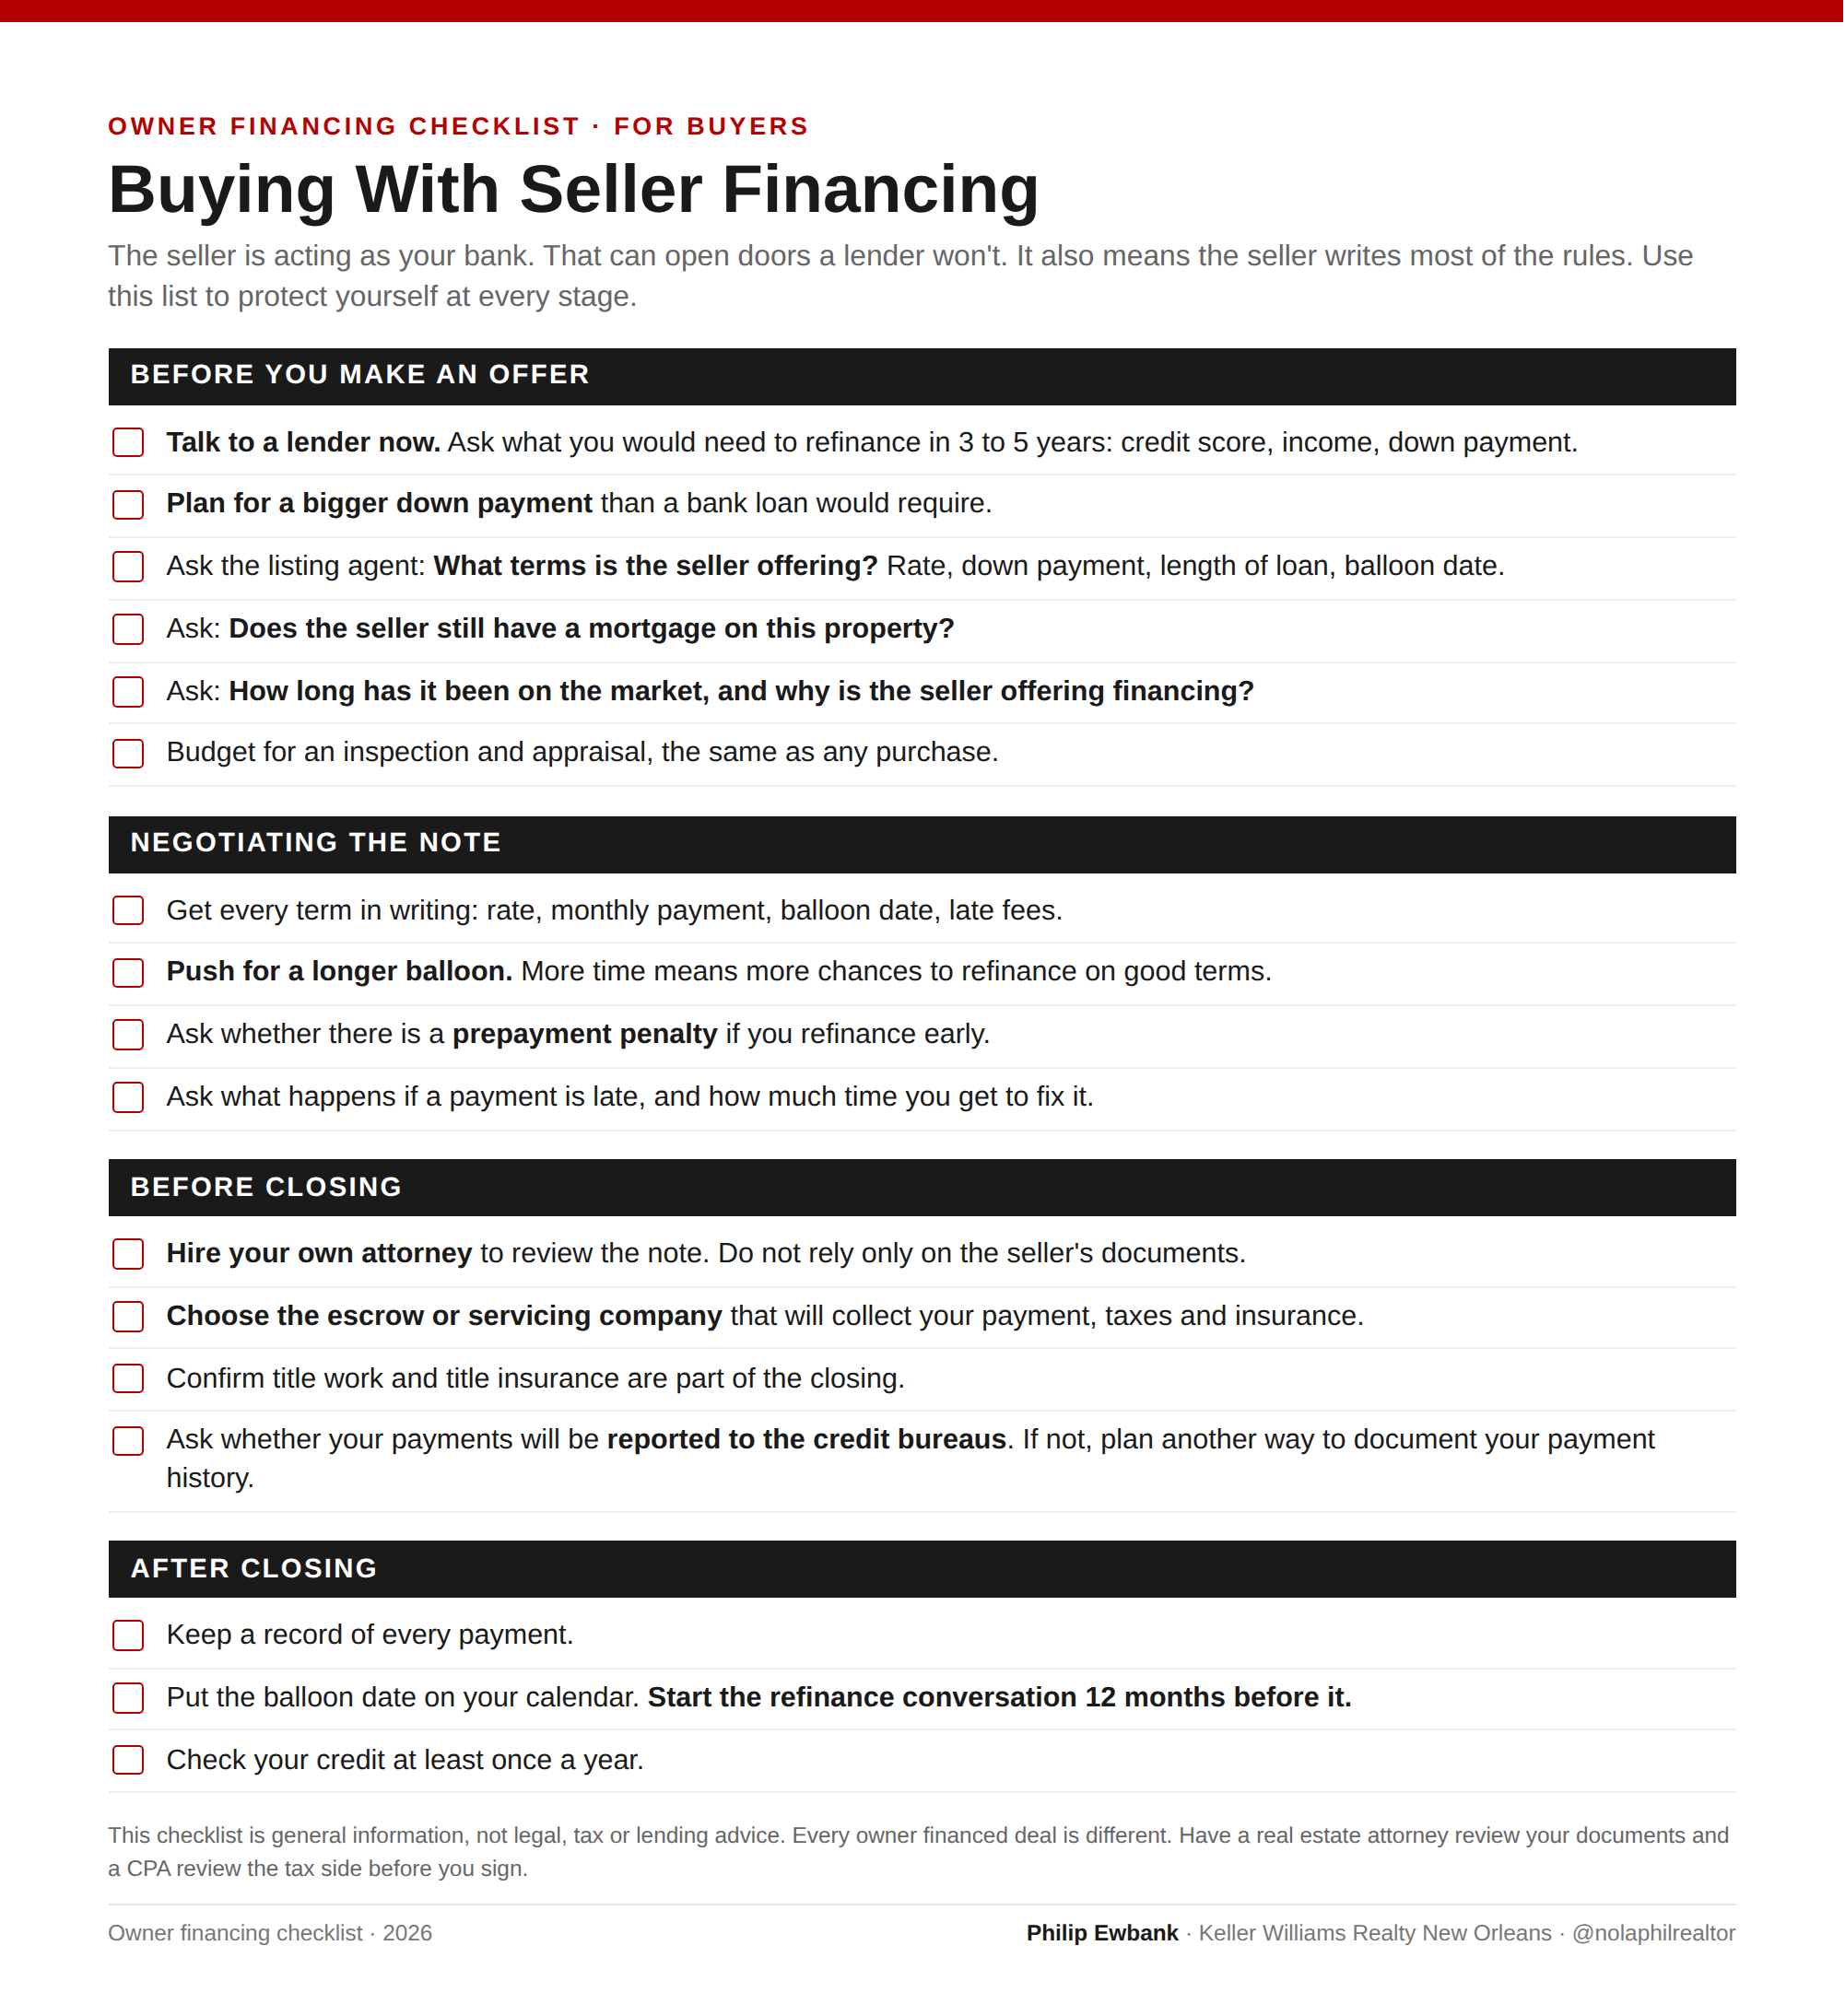
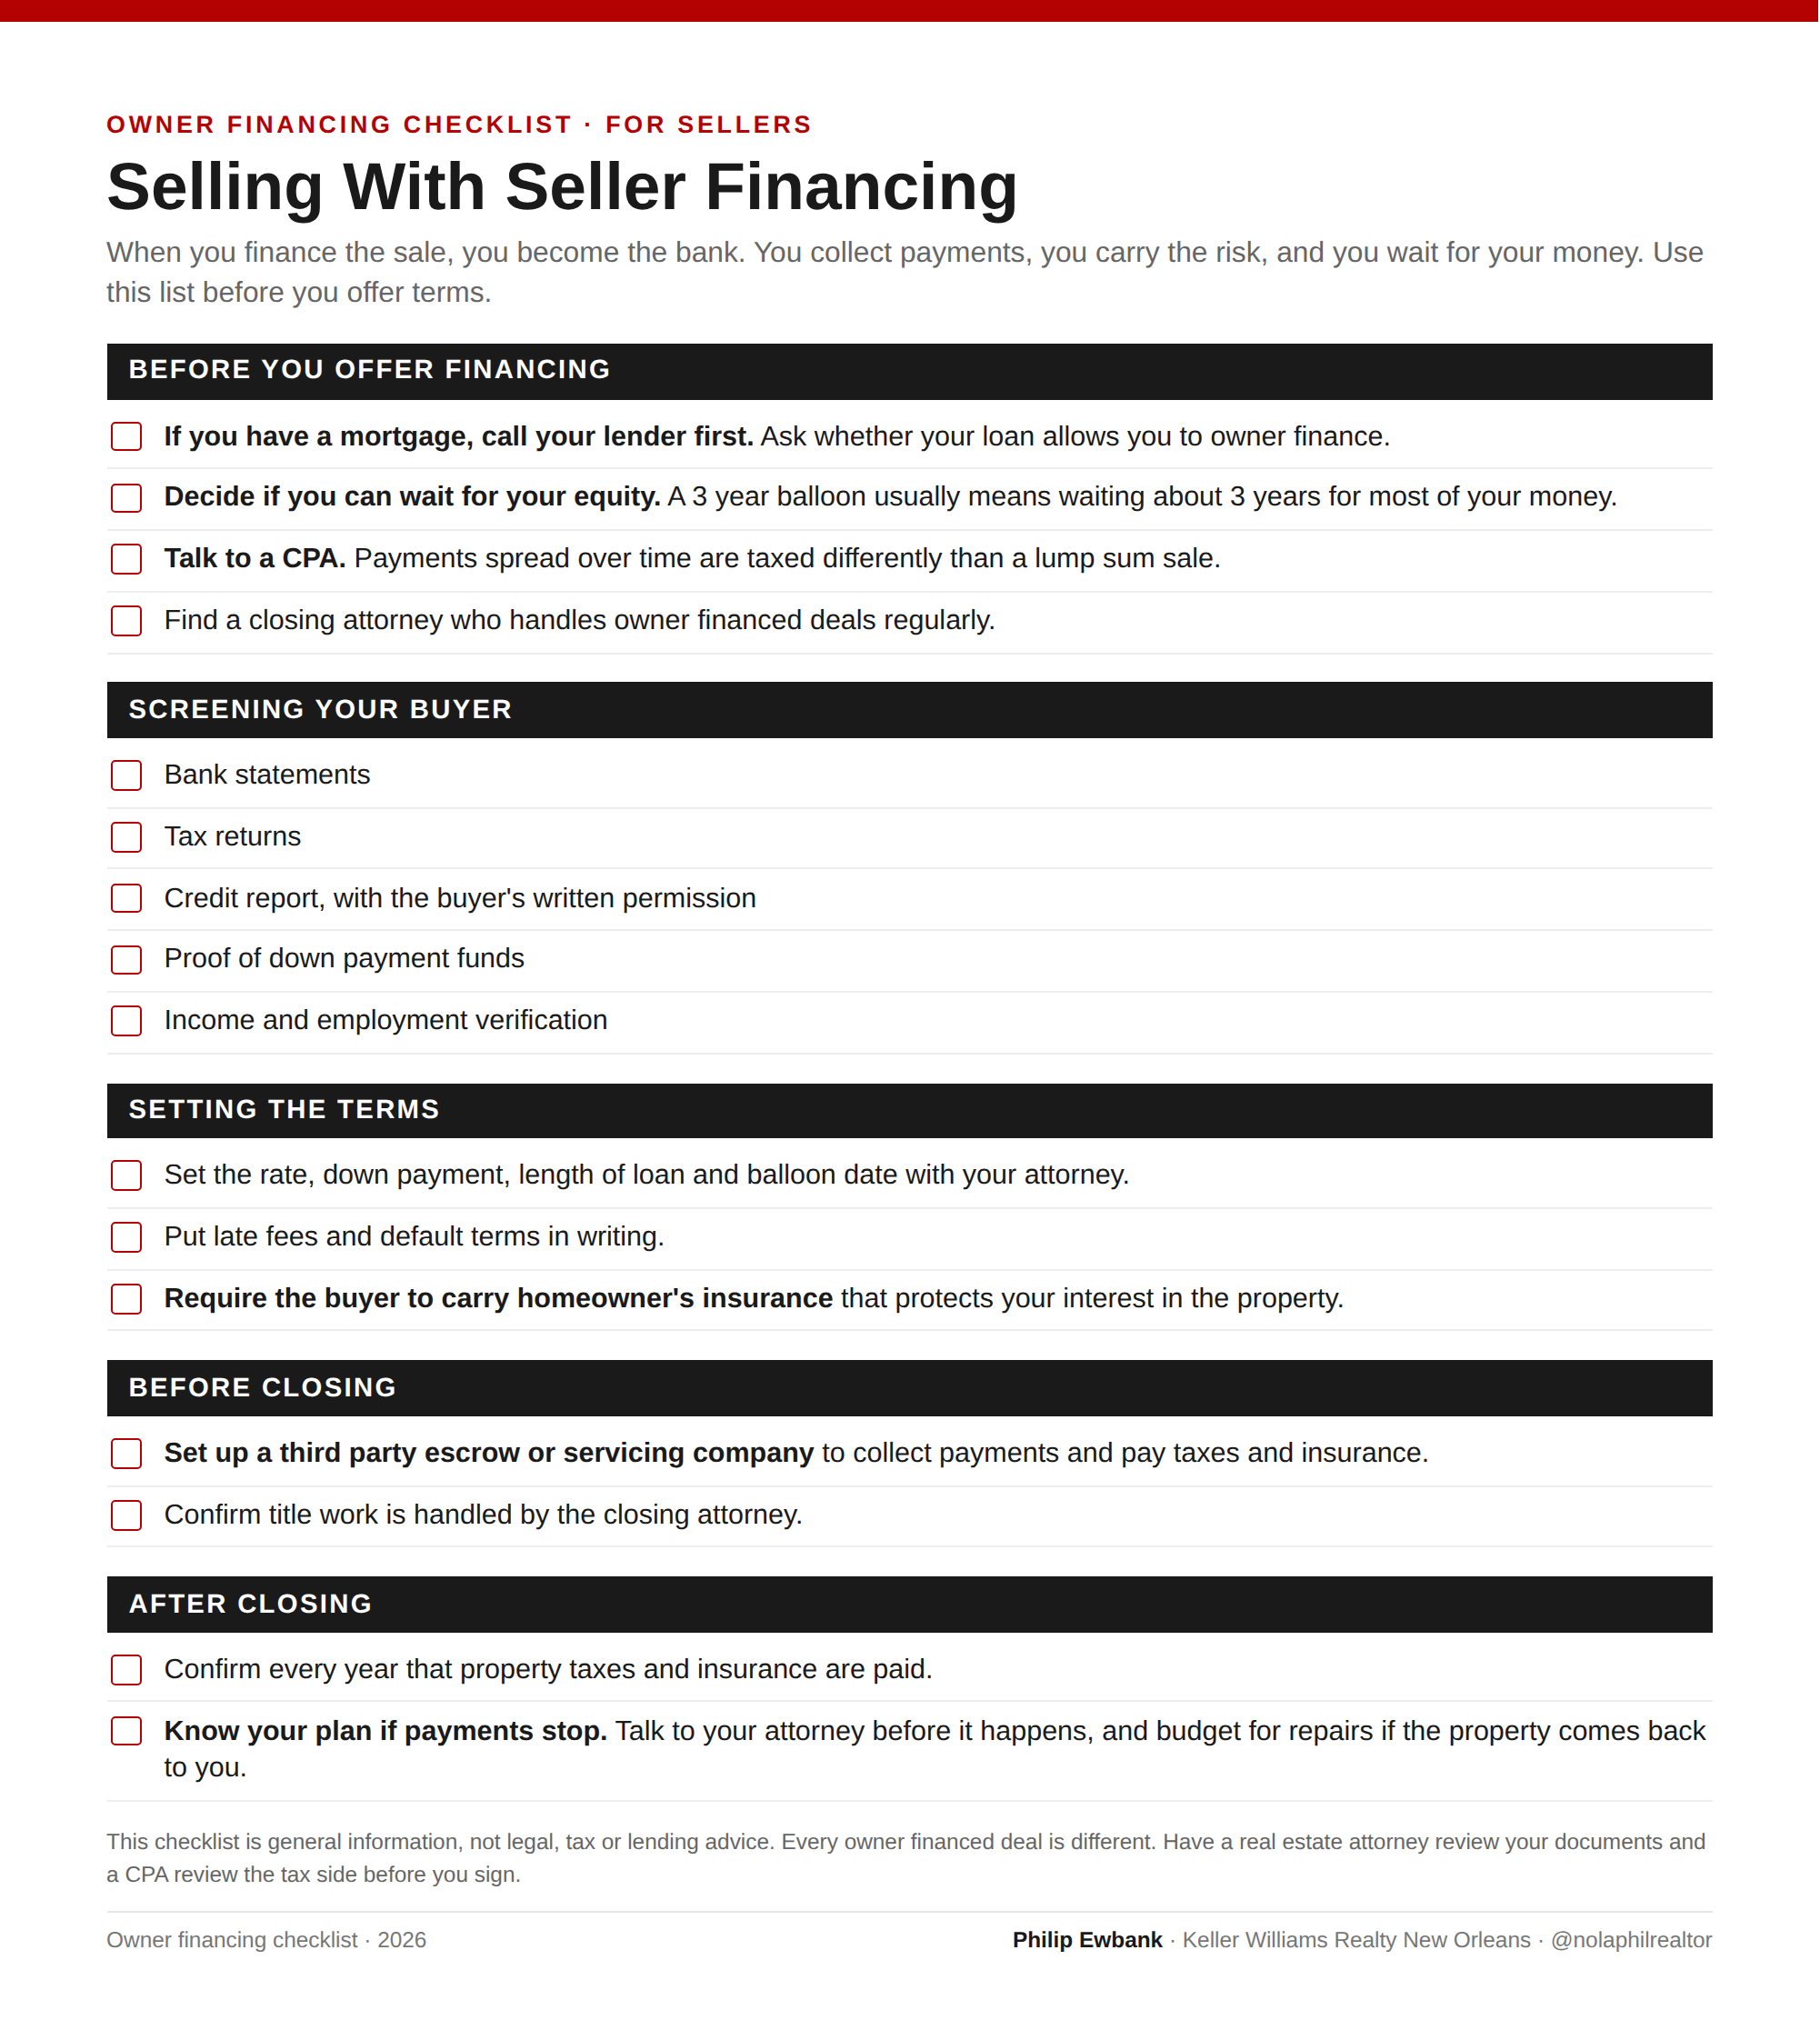
Would a seller-financed deal make sense for you right now, or does the balloon risk take it off the table?
🏠🏠🏠🏠🏠🏠🏠🏠
Philip Ewbank,
Realtor Keller Williams Realty New Orleans
8601 Leake Ave, New Orleans, LA 70118
C: 504.335.7481 | O: 504.862.0100
Each office independently owned & operated. Licensed in the state of Louisiana. License #0995700196