

Are you nervous about buying a house?
Good!
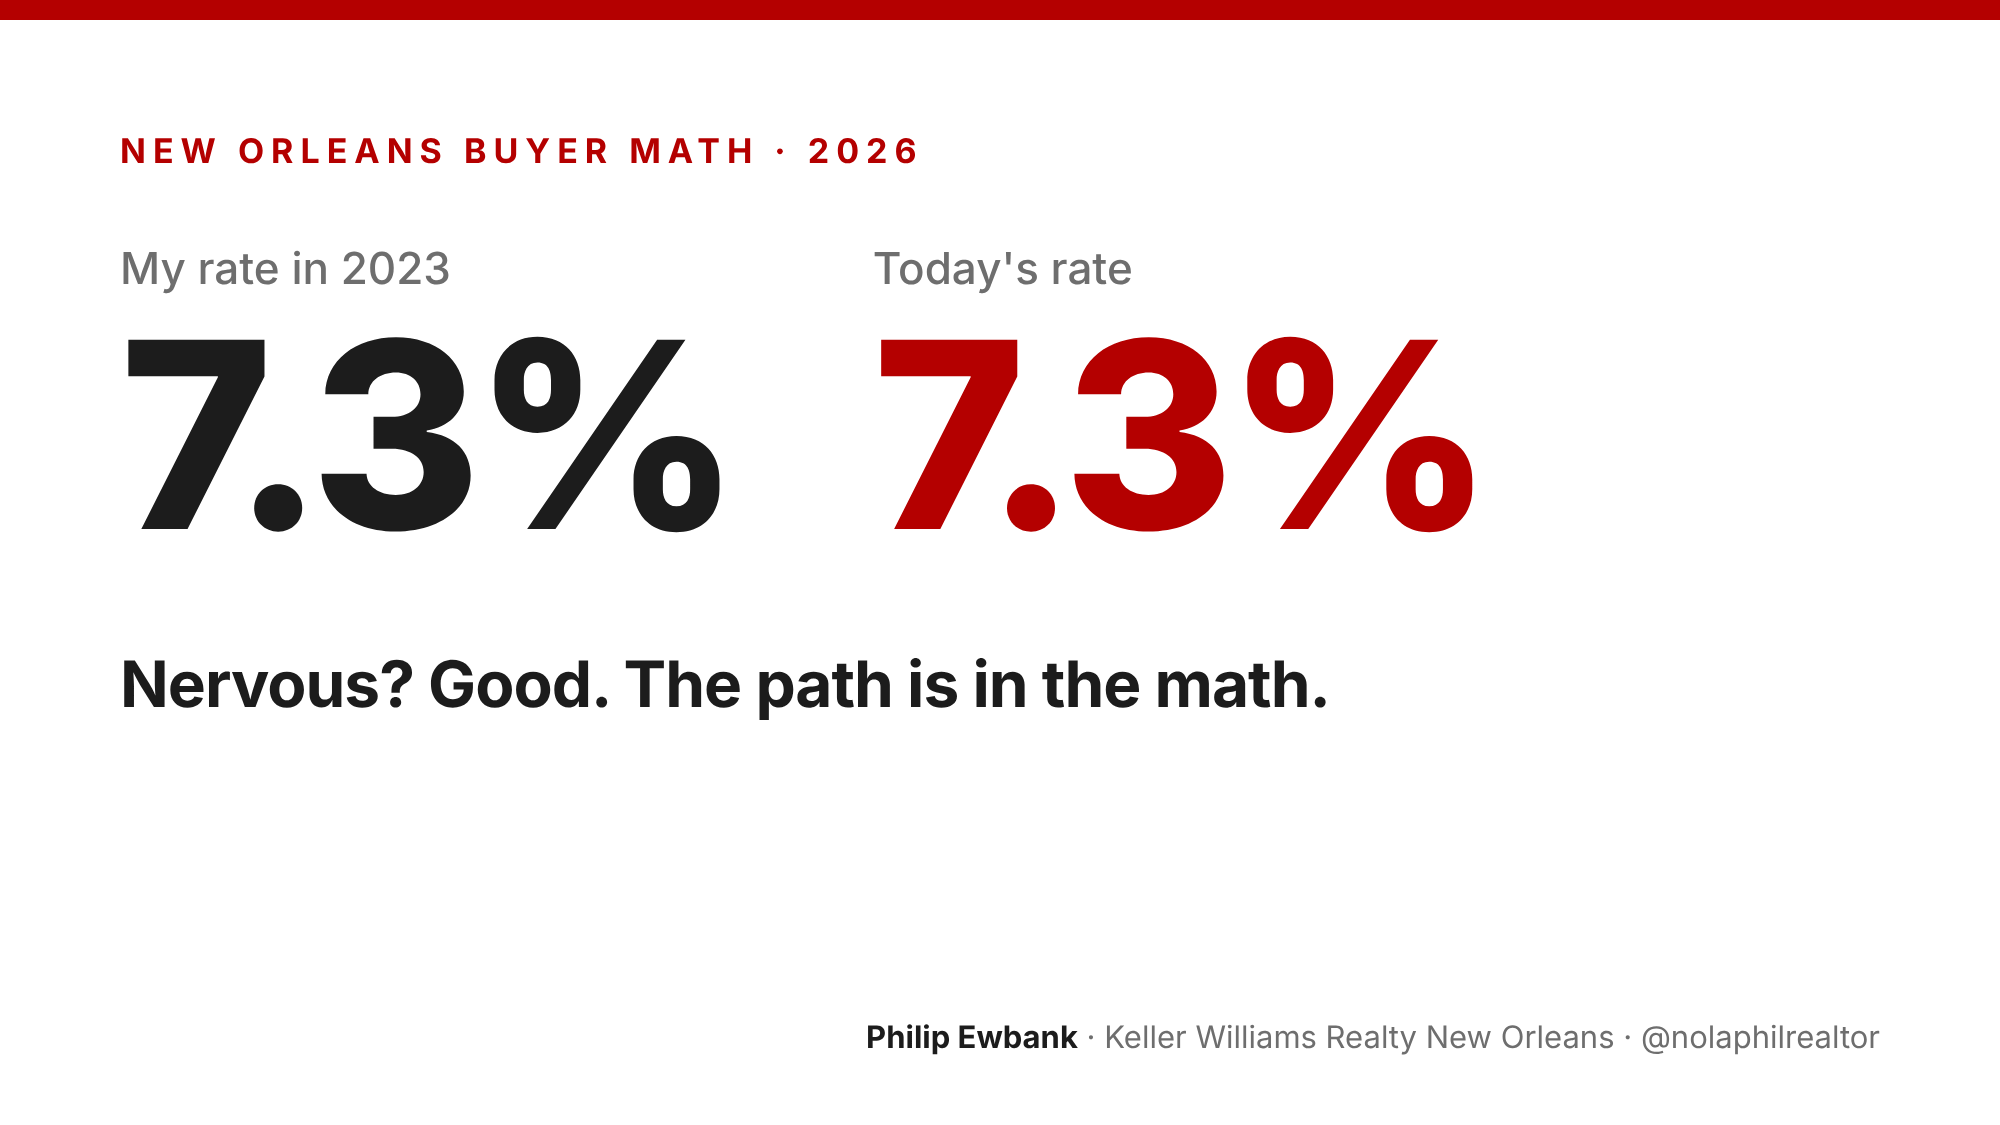
It can be nerve-wracking. When Susie and I bought our house in 2023 with a 7.3% interest rate, I was beside myself with second-guessing.
Was this the right move?
Why didn’t I buy a double?
Who buys a home at this interest rate?
Today’s rates are sitting right around where ours were. So if you’re feeling what I felt, you’re not crazy.
And if anyone tells you not to be nervous, or that you have to act right now, that’s not advice. That’s malpractice.
Buying a home is a big deal. There’s a reason people congratulate you when you do it.
But at the end of the day, the path was in the math.
In the fall of 2023, New Orleans was in a severe buyer’s market. Susie and I negotiated over $50,000 in price and concessions on a house that would cost considerably more today.
Our biggest concern was wind and hail insurance. How bad would it hit our mortgage note, and how would we find out?
Here’s what I’ve learned about nerves:
Pessimistic and uninformed = a toxic spiral of paranoia
Optimistic and uninformed = an ostrich
Informed optimism = the energy to make bold decisions with data behind you
Knowing our monthly note would swing with insurance, Susie and I ordered a wind mitigation survey.

After submitting the wind mitigation report to our home insurance provider we shaved $2,500 off the annual premium. Think I slept better?
What does that look like for you?

Here’s what’s on the table for most buyers right now:
What could a 2-1 buydown do for you at today’s rates?
How much could we negotiate off the sales price?
What can be done to reduce your insurance?
How much can a seller contribute to your closing costs?
What grants are out there to help with your down payment?

Buying a home is expensive. Duh… Buying a home without snagging all your advantages, well that’s dumb.
Let’s look at what buying a home can look like at $400,000 in New Orleans.
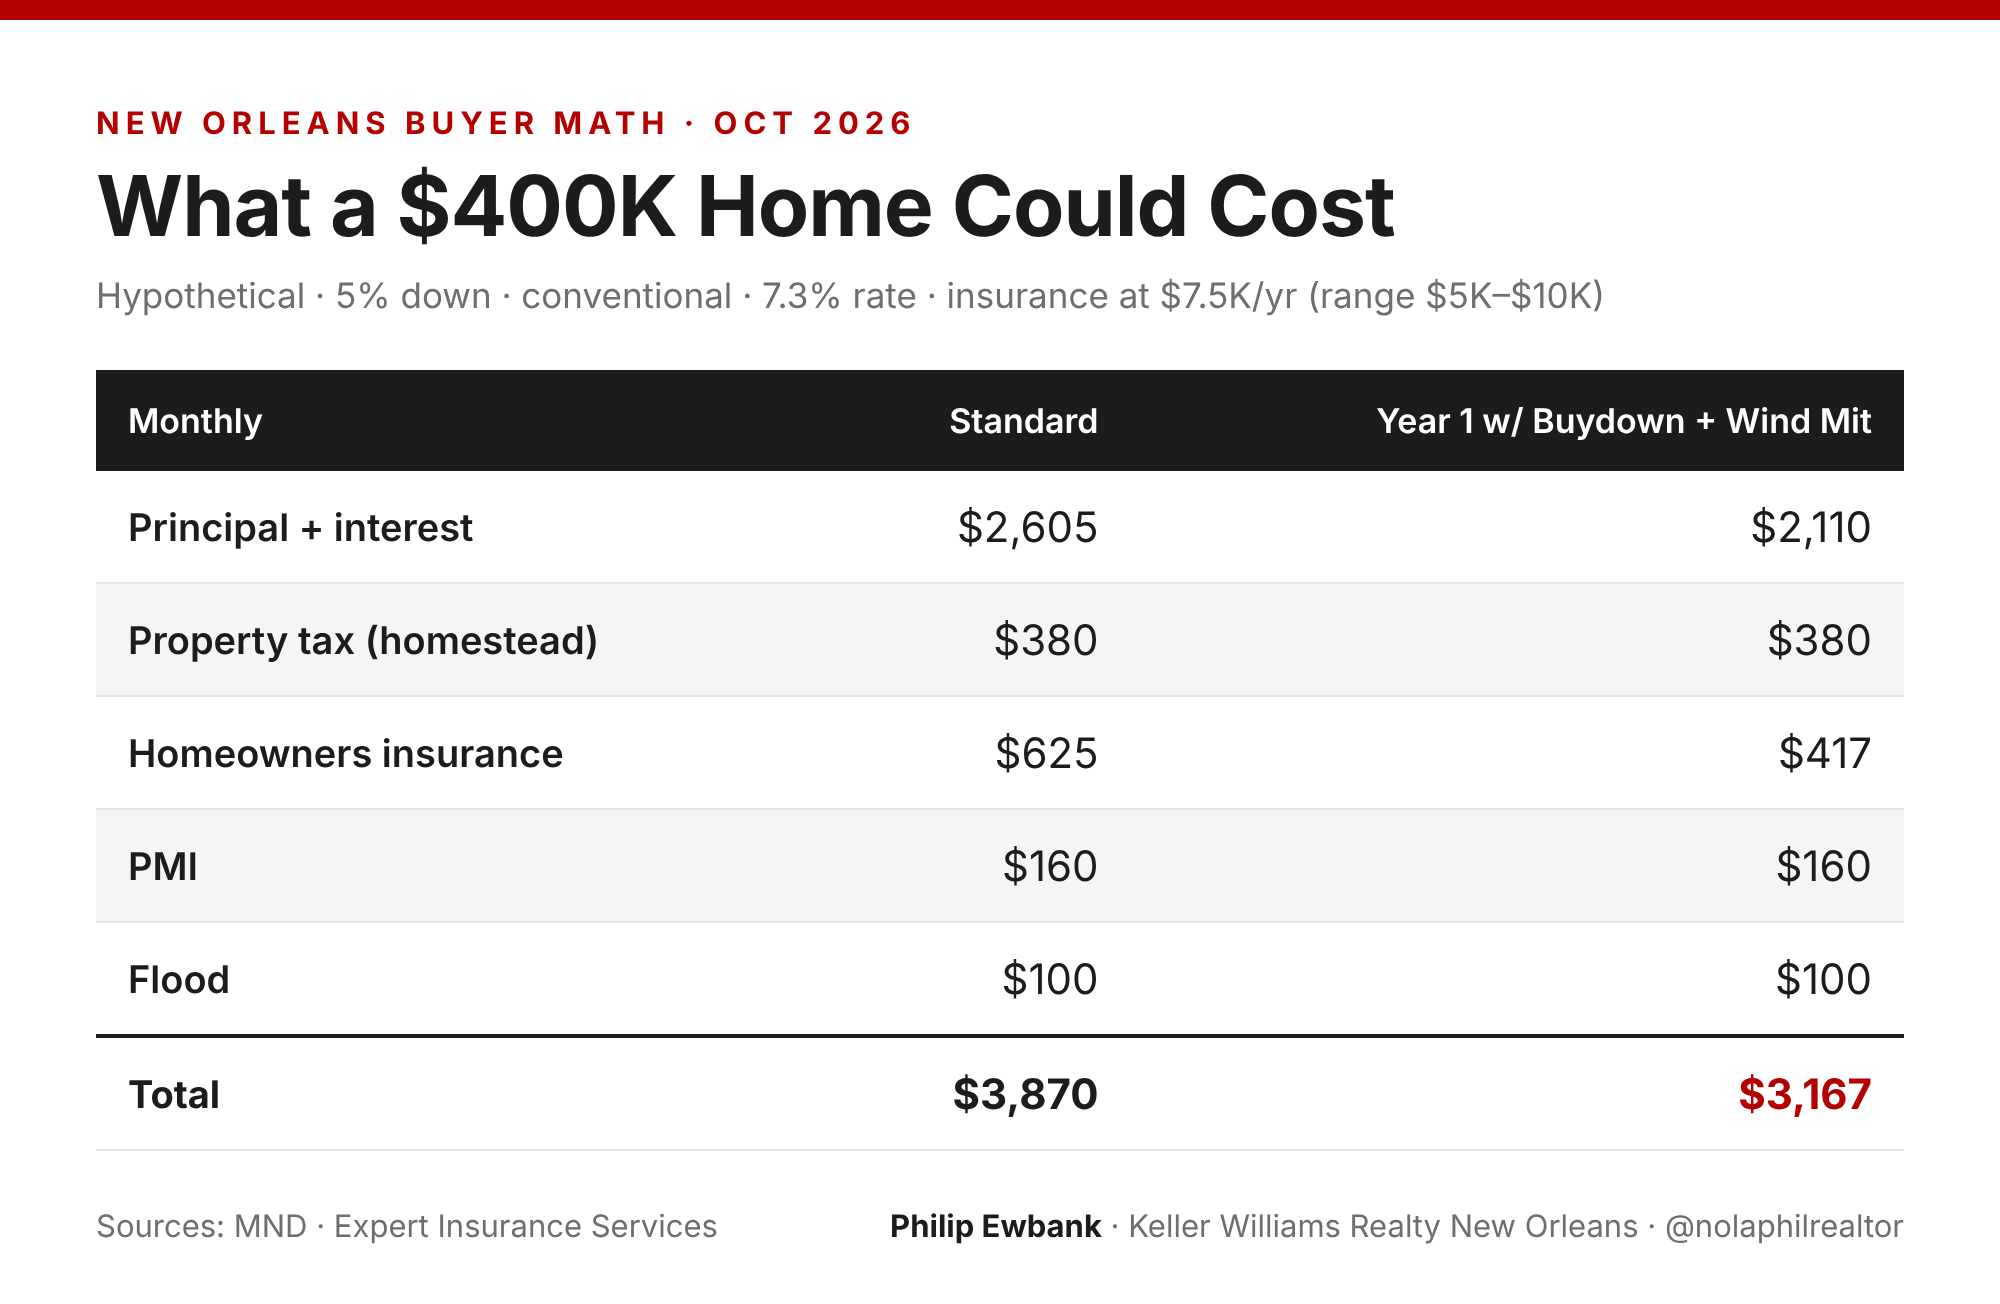
Now let’s use the advantages:
A 2-1 buydown drops principal and interest to about $2,100 in year one and $2,340 in year two
It costs about $9,000, which fits under the 3% seller concession cap ($12,000)
A wind mitigation credit like ours takes about $208/month off insurance
Year one total: about $2,960 instead of $3,660
That’s $700 a month. Same house, same rate…!
Mortgage math courtesy of Cameron Budzius, The Mortgage Krewe. Insurance estimates courtesy of Chris Kirkwood, Expert Insurance Services.
So...
Remember, real estate is one of the only assets you can directly improve!
Your shares of Apple stock, your copy of The Amazing Spider-Man #1 or that Krugerrand you inherited can’t grow in value because of anything you do. Your home can.
If you’re a first-time buyer: Your nerves are valid. Use them to ask better questions.
If you’ve been waiting on rates: I bought at 7.3%. The rate is one number. The negotiation, the concessions and the insurance are the rest of the math.
If you’re already house hunting: Make sure your agent is showing you all of this before you write an offer.
I’m Philip Ewbank. If you want to run your numbers, no pressure, I’m here.
🏠🏠🏠🏠🏠🏠🏠🏠
Philip Ewbank,
Realtor Keller Williams Realty New Orleans
8601 Leake Ave, New Orleans, LA 70118
C: 504.335.7481 | O: 504.862.0100
Each office independently owned & operated. Licensed in the state of Louisiana. License #0995700196